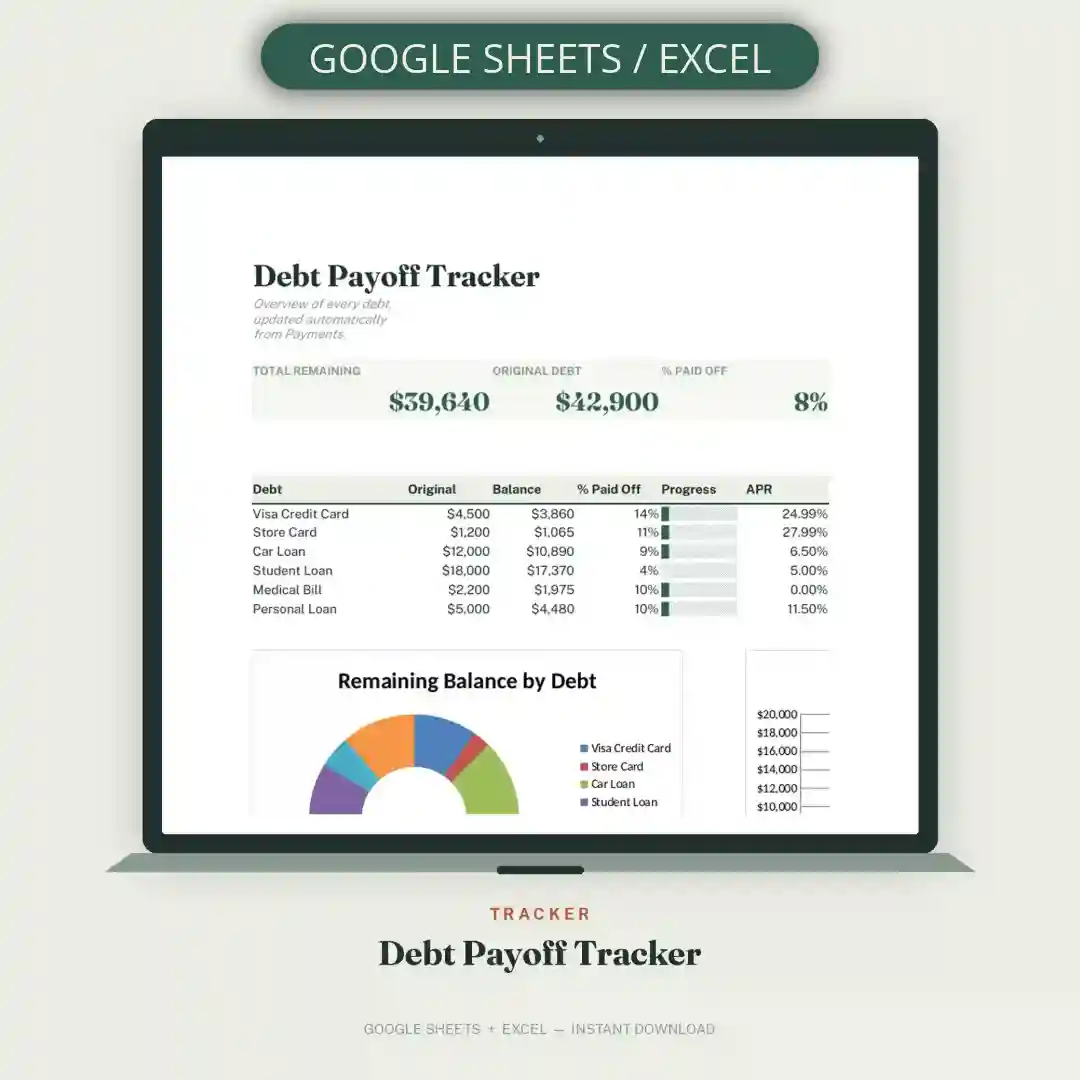
Debt Payoff Tracker
-
Calculate both orders automatically.
Avalanche (highest interest first) and Snowball (smallest balance first), side by side, so you're choosing with real numbers instead of a hunch. -
Track balance and percent paid off together.
A dollar amount alone doesn't tell you how far you've come. -
Log every payment.
Balances that update automatically are more motivating than a number you have to manually recalculate.
Debt Payoff Tracker FAQ's
Avalanche pays off the highest-interest debt first, saving the most money overall. Snowball pays off the smallest balance first, for faster early wins. This tracker calculates both automatically so you can compare before choosing either one.
No — it tracks your balance based on the payments you log, not a month-by-month interest simulation. It answers what you owe and which order to attack it in, not a full amortization schedule.
Yes. Credit cards, auto loans, student loans, medical bills, and personal loans can all go in the same tracker side by side, ranked against each other automatically.
Yes. Add a new row to Debts Setup with the balance, APR, and minimum payment, and it's automatically included in both ranking orders.
Yes. A 0% APR debt still gets tracked and ranked normally — it naturally sorts to the bottom of the Avalanche order, since there's no interest cost driving urgency.
Yes. Both orders are calculated side by side at all times, so you can change which one you're following without losing any tracked progress.